Global LNG market faces demand cuts as Hormuz disruptions strain supply
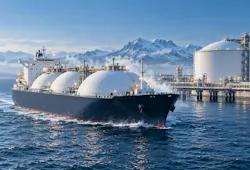
Prolonged disruptions to LNG shipments through the Strait of Hormuz are putting mounting pressure on global natural gas markets, with limited spare liquefaction capacity leaving demand reductions as a key mechanism for restoring market balance.
Despite elevated prices in Europe and the Asia Pacific, alternative suppliers have limited ability to quickly replace lost Gulf exports, raising the prospect of tighter markets extending into 2027.
European gas prices remain elevated as the Northern Hemisphere enters winter with unusually low inventories. Dutch TTF natural gas futures traded around €88/MWh (about $29/MMbtu) on Oct. 19, while EU underground storage stood at 74.6% of capacity as of Oct. 18, compared with a 5-year seasonal average of about 89%. German storage was particularly low, at about 61%.
The Strait of Hormuz remains a major supply constraint. Since the Middle East conflict began in late February, around 80% of previously available LNG exports from Qatar and the UAE have been sidelined. Combined exports averaged 1.73 billion cu m (bcm)/month during March–September, compared with a 5-year pre-crisis average of 9.37 bcm/month. Renewed attacks on commercial shipping have complicated prospects for a sustained recovery in shipments.
An October analysis by the Oxford Institute for Energy Studies (OIES) suggests that prolonged supply disruptions would be absorbed primarily through reduced LNG imports and demand rather than increased production elsewhere.
Using an April 2027 restart of Gulf LNG exports as its modeling baseline, OIES estimates that delaying the recovery until October 2027 would create a 49-bcm supply gap in 2027 relative to that baseline. Other exporters would provide only 7.3 bcm of additional supply, leaving 41.7 bcm, or 85% of the shortfall, to be absorbed through lower imports and demand.
US LNG exports offer limited additional flexibility
US LNG export installations continue operating at high utilization rates, supported by the substantial price differential between domestic and international markets.
Henry Hub futures traded near $3/MMbtu on Oct. 20, far below European prices. US Energy Information Administration (EIA) data showed working gas inventories at 3.57 tcf for the week ended Oct. 9, following a 67-bcf injection. Stocks were 1.3% above the 5-year average, although the surplus narrowed from 2% the previous week.
Meanwhile, LNG feedgas demand has remained strong. Deliveries averaged about 18 bcfd in September, up 4.4% from August, according to American Gas Association data citing Rystad Energy.
However, strong domestic gas production and favorable export economics do not necessarily translate into substantially greater LNG shipments in the near term. Existing liquefaction capacity and the timing of new project start-ups remain key constraints.
OIES modeling suggests that US LNG exports would change little relative to its baseline across the different 2027 Hormuz scenarios, despite the potential for growth from new capacity additions. Based on OIES modeling, Australia would provide most of the incremental supply response.
Different adjustment pressures
With limited scope for additional LNG supply, importing regions would bear most of the adjustment burden.
Under the OIES October 2027 restart scenario, European LNG imports would decline by 20.8 billion cu m relative to the April restart baseline, accounting for about half of the global demand adjustment. China's imports would fall by 6.6 billion cu m, followed by a 5.4-billion cu m reduction in South Asia.
The impact would vary significantly across markets.
In Europe, much of the adjustment would come through reduced summer storage injections rather than immediate cuts in consumption. Already-low inventory levels raise the risk that prolonged supply disruptions could leave storage insufficiently replenished ahead of winter 2027–28, extending pressure into another heating season.
South Asian importers would face more direct demand reductions. Sustained high LNG prices could force some buyers to reduce consumption, switch to coal or oil, or face power shortages. Japan, South Korea, and Taiwan would be comparatively insulated because of their greater ability to secure higher-priced cargoes.
Disruption duration drives price outlook
The timing of a sustained reopening of Hormuz remains central to the gas price outlook.
Under the OIES baseline assuming an April 2027 recovery, European TTF prices would fall to $16.05/MMbtu in first-quarter 2027 and $12.39/MMbtu in the second quarter, as the market anticipates returning Gulf supply.
A delayed recovery until October 2027 would instead push TTF to a peak of $31.35/MMbtu in second-quarter 2027. Continued restrictions through 2028 would produce a similar peak of $32.05/MMbtu. A partial recovery to 50% of pre-crisis output beginning January 2027 would produce a smaller price response, with TTF peaking at $18.42/MMbtu in first-quarter 2027.
Current forward prices remain substantially above the OIES April restart scenario, indicating that traders continue to price in significant uncertainty over the timing of supply recovery.
About the Author
 Conglin Xu
Managing Editor-Economics
Conglin Xu, Managing Editor-Economics, covers worldwide oil and gas market developments and macroeconomic factors, conducts analytical economic and financial research, generates estimates and forecasts, and compiles production and reserves statistics for Oil & Gas Journal. She joined OGJ in 2012 as Senior Economics Editor.
Xu holds a PhD in International Economics from the University of California at Santa Cruz. She was a Short-term Consultant at the World Bank and Summer Intern at the International Monetary Fund.