Devon takes more divestitures off the table
Devon Energy Corp., Houston, has concluded a strategic review of its portfolio after buying Coterra Energy and striking a deal to sell its Eagle Ford assets but president and chief executive officer Clay Gaspar said Nov. 6 that he and the company’s directors “will not hesitate” to strike other deals if they’re good for shareholders.
On a conference call discussing Devon’s third-quarter results, Gaspar said the months since Devon bought Coterra and he said his team would take a fine-toothed comb through its holdings in six basins have been “taxing” for both employees and investors because of the uncertainty about the company’s strategy. Several investors have pushed Devon’s leaders to sell other assets and focus on the Permian basin or to put the entire company on the block.
That’s not happening in the near future, Gaspar said on the third-quarter call while also saying his team remains open to talking to bidders for its assets.
“We owe it to our investors to […] be thorough, very transparent and very open, but we also found it very important that we drew a line and said, ‘This is the close of this period, this chapter.’” he said. “This chapter being, ‘Everything’s on the table.’”
Assuming the planned $4.2 billion divestiture of its Eagle Ford operations to Crescent Energy Co. goes through, Devon will control about 750,000 net acres in the Permian that produce about 900,000 boe/d as well as a group of what Gaspar called “complementary assets” in the Anadarko (177,000 boe/d), the Williston and Powder River (187,000 boe/d) and the Marcellus (about 2 bcfd).
 Devon Energy Marcellus operations.
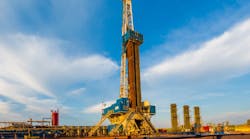 Devon drilling operations
Preliminary plans call for those assets to grow 1-3% in coming years and to receive $5.3 billion in capital spending next year, with three-quarters of that going to the Permian. Early 2027 forecasts call for Devon (ex-Eagle Ford) to grow it total production by 2.6% to 1.6 million boe/d.
“We’re going to work on getting better every single day for the best interest of the shareholders,” Gaspar said when asked about Devon shares trading at a discount to their peers. “I think that clears the path to close this valuation gap and we look forward to being on the road as soon as Monday to meet with more investors, get that feedback and really talk to the opportunity ahead—and really, I think, excite the organization and the shareholders about our clear path forward.”
The end of Devon’s strategic review and Gaspar’s chosen “clear path forward” did not satisfy the investors at TOMS Capital Investment Management, who (along with their peers at Kimmeridge) have pushed for more drastic measures. In a statement Nov. 6, the investors said they are “profoundly disappointed” that Devon is holding station for now but acknowledged that leaders had committed to engage with potential buyers.
Other investors also appear to be let down: In afternoon trading, shares of Devon (Ticker: DVN) were down 1.4% to $42.26 while many of its U.S. peers were in the green. Over the past 6 months, they’re lost nearly 10% of their value, which has cut the company’s market value to $46.5 billion.
About the Author
 Geert De Lombaerde
Senior Editor
A native of Belgium, Geert De Lombaerde has more than two decades of business journalism experience and writes about markets and economic trends for Endeavor Business Media publications Healthcare Innovation, IndustryWeek, FleetOwner, Oil & Gas Journal and T&D World. With a degree in journalism from the University of Missouri, he began his reporting career at the Business Courier in Cincinnati and later was managing editor and editor of the Nashville Business Journal. Most recently, he oversaw the online and print products of the Nashville Post and reported primarily on Middle Tennessee’s finance sector as well as many of its publicly traded companies.

