IEA: Oil supply rebound remains fragile; diesel tightness persists
Global oil markets are expected to remain in deficit through yearend despite a sharp contraction in demand, as renewed Middle East attacks threaten a recovery in supply, the International Energy Agency (IEA) said in its Oct. 14 Oil Market Report.
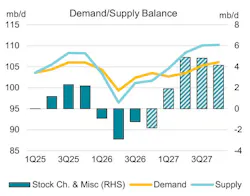
The agency forecasts world oil demand will fall by 2.6 million b/d to 102.4 million b/d in 2026 as high fuel prices and a deteriorating economic outlook weigh on consumption. Fourth-quarter demand is projected to decline by 2.5 million b/d from a year earlier.
Demand is expected to recover by 2 million b/d in 2027, leaving consumption 620,000 b/d below 2025 levels. IEA reduced its forecast for next year’s demand growth by 560,000 b/d from September.
Supply recovery at risk
Global oil supply increased by 2.5 million b/d month over month to 102.3 million b/d in September. OPEC+ accounted for 2.1 million b/d of the increase, led by Saudi Arabia. Renewed attacks on tankers and energy infrastructure threaten further gains, IEA warned.
Despite September’s rebound, global supply is forecast to decline by 5.8 million b/d to 100.7 million b/d this year, before rising by 7.7 million b/d in 2027. Next year’s recovery remains contingent on sustained improvements in Hormuz flows.
"Crude oil exports from Gulf producers, led by Saudi Arabia, surged by 4.4 million b/d to 13.9 million b/d in September, reaching over 75% of pre-war levels as supply recovered strongly and inventories were drawn down. Robust Gulf of Oman ship-to-ship transfers helped lift total oil flows through the Strait of Hormuz by 3.7 million b/d to 10.9 million b/d, while the swift return of East-West pipeline flows increased overall bypass exports by 970,000 b/d to 5.6 million b/d. The strong rebound raised estimated global supply for third-quarter 2026 by 190,000 b/d compared with last month’s Report. However, due to heightened security concerns amid increased Houthi attacks in the region in October, we have left the projections for the remainder of the year largely unchanged," IEA said.
North Sea Dated averaged $116.89/bbl in September, up $26.17/bbl from August.
Diesel, inventories under pressure
Global diesel exports in September were nearly 700,000 b/d below year-earlier levels, as increased shipments from other suppliers only partly offset losses from Russia and the Middle East. IEA expects diesel market tightness to extend well into 2027.
"Refined product and LPG shipments from the Middle East have risen much more slowly than crude oil flows and remain below half of their pre-war levels. Refined products rose by 210,000 b/d to 1.9 million b/d in September, while LPG increased by 90,000 b/d to 670,000 b/d—from pre-war levels of 4.7 million b/d and 1.5 million b/d, respectively. Continued disruptions to Middle East exports, compounded by lower supply from Russia and some Asian countries, cut global diesel/gasoil availability by 1.5 million b/d in second-quarter 2026 and 1.7 million b/d in third-quarter 2026 compared with a year earlier, putting diesel markets under extreme pressure," IEA said.
"While global diesel prices have eased from the all-time highs of more than $200/bbl reached in September, benchmarks remain nearly double the price of crude oil and their pre-crisis levels. Record diesel prices are already having broad economic consequences by raising the cost of goods and impacting real incomes, economic activity, and inflation."
Global refinery runs are projected to reach a seasonal low of 81.3 million b/d in October before recovering to 84.6 million b/d by yearend, according to IEA. Higher crude and freight costs have squeezed European and Asian refining margins, while discounted feedstocks have supported record US margins.
Global observed oil inventories fell by 10 million bbl in September, as a 113-million-bbl onshore draw exceeded a 103-million-bbl increase in oil on water. Observed non-OECD inventories was down by a sizeable 76 million bbl, of which Chinese onshore crude accounted for 59 million bbl. Stocks ended September 509 million bbl below end-February levels, with onshore inventories hovering at their lowest since at least 2016.